From Jewelry to Collectibles: Assets Some Homeowners Consider Selling to Cover Missed Mortgage Payments
Falling behind on mortgage payments can be stressful and overwhelming.
Whether the cause is a job loss, reduced work hours, unexpected medical expenses, divorce, or another financial setback, many homeowners in Prince George's County and throughout Maryland eventually find themselves looking for ways to generate extra cash.
One option some homeowners consider is selling personal belongings they no longer use.
From jewelry and collectibles to electronics and recreational vehicles, many households own assets that may have resale value. While selling personal property isn't the right solution for everyone, it can sometimes provide temporary financial relief while you explore longer-term options.
This guide explains some of the assets homeowners commonly consider selling, important factors to think about before selling, and other mortgage assistance options that may be available.
Why Some Homeowners Look for Extra Cash When Mortgage Payments Fall Behind
When financial challenges arise, homeowners often look for ways to improve cash flow as quickly as possible.
Some people:
Take on additional work
Reduce household expenses
Use savings
Borrow from family members
Explore mortgage assistance programs
Sell personal belongings
The goal is usually to create enough financial breathing room to cover missed mortgage payments, avoid further delinquency, or gain time while developing a long-term plan.
Every homeowner's situation is different, but understanding your available resources can help you make informed decisions.
Before Selling Anything, Start With a Financial Assessment
Before listing items for sale, it can be helpful to take a step back and evaluate your overall situation.
Ask yourself:
How many mortgage payments have been missed?
How much money is needed to catch up?
Is the hardship temporary or ongoing?
Will selling assets solve the problem or only provide short-term relief?
Are there mortgage assistance options available?
Understanding the scope of the challenge can help you determine whether selling assets makes sense and how much cash you realistically need to generate.
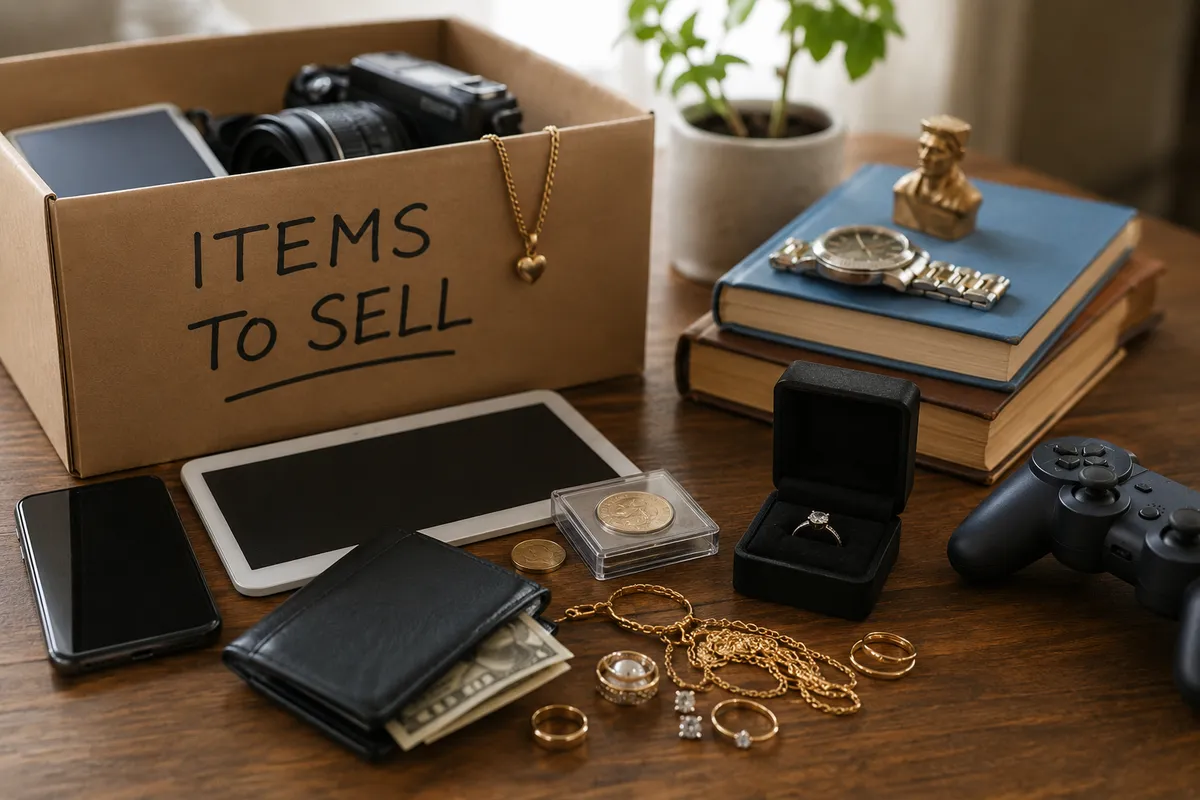
Jewelry and Precious Metals
Jewelry is often one of the first categories homeowners consider because certain pieces may retain significant value.
Items that may have resale potential include:
Gold, silver, platinum, or etc. jewelry
Diamond rings
Luxury watches
Gold or silver coins
Precious metal bullion
Many families have jewelry tucked away in drawers, safes, or jewelry boxes that is rarely worn.
Before selling, consider obtaining multiple appraisals or offers. Values can vary significantly between buyers, and taking time to compare options may help you maximize proceeds.
It's also important to carefully consider sentimental items that may be difficult or impossible to replace.
Collectibles and Memorabilia
Many homeowners are surprised to learn that certain collectibles may be worth substantially more than expected.
Examples include:
Sports memorabilia
Trading cards
Comic books
Vintage toys
Antiques
Rare coins
Stamps
Autographed items
Historical collectibles
In recent years, some collectible markets have experienced significant growth, particularly for rare and well-preserved items.
Researching recent sales and consulting with reputable buyers can help you better understand an item's market value before making a decision.
Electronics You No Longer Use
Technology tends to accumulate over time.
Many households have closets, drawers, or storage areas filled with devices that are no longer being used.
Potentially valuable electronics include:
Smartphones
Tablets
Laptops
Desktop computers
Cameras
Gaming systems
Smart watches
Audio equipment
While individual devices may not generate substantial amounts of money, selling several unused items together can sometimes provide meaningful financial support.
As a bonus, decluttering your home may make the process feel more productive and manageable.
Vehicles, Boats, and Recreational Equipment
Larger assets often offer greater opportunities to raise funds quickly.
Some homeowners consider selling:
A second vehicle
Motorcycles
Boats
RVs
Campers
ATVs
Jet skis
Recreational trailers
For households that own multiple vehicles or recreational assets that are rarely used, selling one may provide a significant financial boost.
However, transportation and lifestyle needs should be carefully evaluated before making any decision.
Tools, Equipment, and Household Assets
Many homeowners own equipment that spends most of its time sitting in a garage, shed, basement, or storage area.
Items that may have resale value include:
Power tools
Lawn equipment
Exercise equipment
Appliances
Workshop machinery
Furniture
Outdoor equipment
Home improvement materials
Online marketplaces have made it easier than ever to connect with local buyers and determine current market demand.
Even smaller sales can add up and help reduce financial pressure.
How to Determine What an Item Is Really Worth
One common mistake homeowners make is underpricing valuable assets.
Before selling anything, consider:
Reviewing recent online sales
Comparing listings on multiple marketplaces
Obtaining professional appraisals when appropriate
Seeking multiple offers
Researching collector demand
Taking a little extra time to understand an item's value may help you avoid leaving money on the table.
Questions to Ask Before Selling Personal Property
Before selling any asset, it's worth asking a few important questions.
Is This Item Essential?
Consider whether the item plays an important role in your daily life.
Will I Need to Replace It Later?
Some assets can be expensive to repurchase if your financial situation improves.
Does It Have Significant Sentimental Value?
Family heirlooms and meaningful possessions often carry emotional value that extends beyond their market price.
Will Selling It Meaningfully Improve My Situation?
If an item only generates a small amount of money relative to your financial need, it may not solve the underlying problem.
Thinking through these questions can help prevent regret later.
Selling Assets Is Only One Possible Solution
While selling belongings can provide temporary relief, it isn't the only option available to homeowners experiencing financial hardship.
Other possibilities may include:
Contacting your mortgage servicer
Applying for mortgage assistance programs
Requesting a loan modification
Exploring repayment plans
Seeking mortgage forbearance options
Meeting with a HUD-approved housing counselor
Creating a household budget review
In many situations, combining multiple strategies may be more effective than relying on asset sales alone.
Maryland Homeowners Should Explore Assistance Early
One of the most important steps homeowners can take is seeking information early.
The sooner you contact your mortgage servicer and learn about available options, the more flexibility you may have.
Maryland homeowners may benefit from educational resources available through:
HUD-approved housing counselors
Maryland Department of Housing and Community Development
Maryland Courts
People's Law Library of Maryland
These resources can help homeowners better understand available mortgage assistance and foreclosure prevention options.
When Bigger Financial Decisions May Be Necessary
Sometimes selling a few items is enough to help a homeowner get back on track.
Other times, financial challenges persist even after valuable assets have been sold.
If you're continuing to struggle despite your efforts, it may be time to take a broader look at your overall financial situation and housing options.
Gathering information early often leads to more choices and better decision-making.
Frequently Asked Questions
Can selling jewelry help me catch up on mortgage payments?
In some situations, yes. The amount depends on the type of jewelry, its condition, and current market demand.
What household items usually have the highest resale value?
Jewelry, vehicles, collectibles, electronics, tools, and certain recreational assets often have strong resale potential.
Should I sell family heirlooms to make mortgage payments?
This is a personal decision. Many homeowners carefully weigh the emotional value of an item against the financial benefit before selling.
Are there mortgage assistance programs available in Maryland?
Yes. Depending on your circumstances, mortgage servicers, housing counselors, and government resources may provide information about available assistance programs.
What should I do if selling belongings isn't enough?
If selling assets doesn't resolve the problem, consider speaking with your mortgage servicer, reviewing mortgage assistance options, and consulting with a HUD-approved housing counselor.
Is it better to contact my lender before selling assets?
In many cases, yes. Understanding available mortgage assistance programs may help you make more informed financial decisions.
You May Have More Options Than You Think
Financial setbacks can happen to anyone.
If you're behind on mortgage payments in Prince George's County or elsewhere in Maryland, you're certainly not alone.
Selling unused assets may help create temporary financial relief, provide breathing room, or help cover missed payments. For some homeowners, it becomes part of a successful recovery plan. For others, it's only one piece of a larger solution.
The most important thing is understanding all of the options available to you before making major financial decisions.
If you'd like to discuss your situation and learn more about potential mortgage assistance options, call or text Kareem Aaron at 301-579-7797. A conversation may help you better understand the choices available and the next steps to consider.